We find out about the renewal two weeks before it binds.
Without X-dates, you call when the incumbent has already re-marketed and the owner is tired of talking about insurance. The real window is three to four months earlier.
We call owners, CFOs and operations leaders, learn their renewal dates and pain points, and book the review meeting while there is still time to market their account.
We find out about the renewal two weeks before it binds.
Without X-dates, you call when the incumbent has already re-marketed and the owner is tired of talking about insurance. The real window is three to four months earlier.
My producers would rather service their book than cold call.
Service work feels safe and pays renewals. New business calls are rejection all day, so they get pushed to Friday afternoon.
Every owner says, 'I've used the same agent for twenty years.'
Loyalty is real, but so is a premium jump or a non-renewal letter. You need to be the second opinion they remember when that happens.
The office manager screens everything. The owner never hears from us.
Front desks and office managers are trained to stop insurance and lending calls. Without a reason and a name, the message dies at the desk.
Guy Carpenter, via The Insurer. Softer markets push buyers to shop their renewals.
BLS Occupational Outlook Handbook, May 2024.
SHRM cost-per-hire benchmark.
When buyers start shopping, the agency that already has the X-date gets the first call.
We act as your new business desk. You choose the classes of business, industries and territory. We fill your producers' calendars.
Contractors, trucking, manufacturing, restaurants, habitational, professional services. We build lists by industry, size and location so the risks match your markets and appetite.
Even when an owner says no, we ask when the policy renews and log it in your CRM or agency management system. Those dates become your next quarter's pipeline.
We call business owners, CFOs, controllers and COOs during their business hours, and handle the office manager politely but persistently.
We book review meetings 90 to 120 days before expiration, so your team has time to gather loss runs, market the account and present options.
For lenders and finance firms, we find owners planning equipment purchases, expansions or a new location, and book a call to talk options.
Every meeting we book has passed all four checks. Here is what each one means for your buyers.
The lines and rough premium size they carry today, or for lenders the amount and purpose of financing, checked against your minimums.
The owner, CFO or controller who decides, plus any partner or board who signs off.
A reason to look, such as a premium jump, non-renewal, new contract requirements, coverage gaps, growth or a financing need.
The X-date for each major line, ideally 90 to 120 days out, or the date funds are needed.
For small commercial accounts, the owner decides and often signs personally. In mid-market companies, the CFO or controller owns insurance and financing, with the COO or HR director involved for workers' comp and benefits. Contractors may have a risk manager or a project executive who cares about certificate requirements. Property owners and HOA boards buy through a property manager.
We open with something specific to the business, never "can I quote your insurance?"
Objections we plan for:
A review meeting is valuable when it is with the right person, at the right time, for an account you can place. Before we book, we confirm:
Your producer gets a CRM note with the business class, approximate revenue and headcount if shared, lines and renewal dates, the incumbent if named, and the owner's words about what is wrong.
Accounts that just renewed are not lost. They become next year's pipeline. Every no comes with an X-date and a follow-up, so your calendar fills on a rolling basis.
Referrals from CPAs, attorneys and happy clients are gold, but they arrive on their schedule, not yours. If you want to build a niche, like contractors or trucking, or open a new territory, you need a pipeline of X-dates you built on purpose.
Here is the kind of opener we would test for an independent agency that writes contractors' general liability, commercial auto and workers' comp. Names are made up.
To the office manager: "Hi, this is Sylvia with Harborline Insurance. I'm not trying to sell anything today. Who handles the company's insurance renewals? I just want to send them a short note." Most office managers will give a name and often an email.
To the owner: "Hi Mike, Sylvia calling for Harborline. We work with a lot of roofing and HVAC contractors in Orlando. Quick question: when does your general liability and auto renew this year?" If he answers, the follow-up is: "How did the last renewal go? Any surprises?"
If Mike says the premium went up or a GC asked for higher limits, that is the meeting: "We'd like to take a look about 120 days before your renewal so there's time to shop it. Could we set 20 minutes in early February?"
If he says he's happy, we thank him, confirm the X-date and set a follow-up for four months before it. No arguing.
Same-day email: Subject: your renewal in May. Two lines: the X-date he shared and a calendar link for a review in the right window.
For business finance firms, the same structure works around a different trigger: an equipment purchase, a building, a new location. For example, the SBA 7(a) program goes up to $5 million for most loans, and owners often do not know where to start.
Florida's market is shifting: Citizens Property Insurance fell below 400,000 policies by late 2025 after private carriers took out more than 546,000 policies, and June 1, 2026 reinsurance renewals came in 15% to 20% lower. Commercial buyers in Tampa, Miami and Orlando have more options to shop.
Florida →TX · Central timeThe Texas Windstorm Insurance Association is the insurer of last resort for wind and hail in 14 coastal counties and part of Harris County, so Houston-area and Gulf Coast businesses often carry a separate wind policy worth reviewing.
Texas →CA · Pacific timeCalifornia approved FAIR Plan commercial limits of up to $20 million per building and $100 million per location, available from July 26, 2025, a sign of how hard commercial property coverage has been to place in wildfire areas.
California →About two to three weeks from first call to first dials. The full process →
 01
We learn your offer, your best customers and what a good meeting looks like for you.
02We build your ideal customer profile, pull and verify target lists, and write call and email scripts for your market.
03Calls, emails and LinkedIn go live in your prospects’ business hours, under one partner’s watch.
 04
Every week you see calls made, conversations held and meetings booked, straight from the CRM.
Before Trifecta, Sylvia called US business owners for a services firm, got past front desks and booked appointments against daily targets, the same work as finding X-dates and booking renewal reviews.
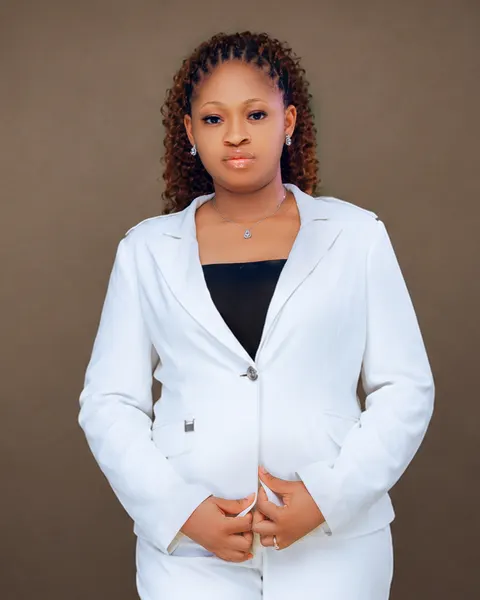
Sylvia worked the phones for a US services firm, calling business owners and decision makers directly. The job was to get past the front desk, introduce the service, qualify interest and book the appointment for the sales team, while logging every outcome and follow-up. She consistently hit daily and weekly booking targets.
Led by Sylvia Owunnachika →
Trifecta is a new agency. These are the partners’ own past roles, shared with their permission and without naming the employer. See the full track record.
Growth SDR fits most agencies and finance firms: a dedicated SDR who books meetings now and builds an X-date pipeline across calls, email and LinkedIn for next quarter.
For owners who need booked meetings now
For teams ready for steady outbound
For companies building a sales function
No, and they do not need to be for what we do. We do not quote, advise on coverage or discuss premiums. We set appointments and capture X-dates. Your licensed producers handle everything that requires a license.
We log them in your CRM, such as HubSpot, Salesforce, Zoho or GoHighLevel. If you work in an agency management system, we agree during setup on how dates and notes get there.
Whichever you write well: contractors, trucking, manufacturing, restaurants, habitational, professional services, healthcare. We build lists around your carrier appetite.
Yes. We book calls with owners and CFOs who are planning equipment purchases, expansions or refinancing. We do not discuss rates or terms. Your team does.
We aim for 90 to 120 days before expiration, which gives your team time to get loss runs and market the account. Earlier dates go into follow-up.
If you sell group benefits, we can target HR directors and owners ahead of their plan renewal. We tune the timing and script during setup.
Our partners are in Nigeria and work US business hours. Your prospects get calls during their workday, and you pay less than you would for an in-house hire.
Book a strategy call. Tell us the classes you write and your territory, and we will show you how we would put renewal reviews on your producers' calendars.